CRS reporting for trusts works in one of two ways: a professionally managed trust that mainly holds financial assets reports itself as a Financial Institution, and every other trust gets reported by the bank that holds its account. Either way, the settlor, the trustees, any protector and the mandatory beneficiaries are reported to their home tax offices every year, and discretionary beneficiaries show up in any year they receive a distribution.
That second sentence surprises a lot of people. Plenty of trust marketing still implies that putting assets into a trust takes your name off the bank’s report. Under the Common Reporting Standard, it doesn’t. The trust becomes a reporting machine with your name in it.
This guide walks through exactly how the rules classify a trust, who ends up on the report, what figure sits next to each name, and the edge cases that catch people out. Every rule here comes from the OECD’s own standard and the tax authorities that apply it.
Put your assets beyond reach in 57 jurisdictions.
Pick where you want your company. We handle the filing, the registered agent, and the bank introduction. From US$1,290, done in days, not months.
- Charging-order protection in jurisdictions courts can't pierce
- Zero tax on foreign income in 30+ territories
- Banking options available
- Fixed price. No surprise fees at closing
How Does CRS Reporting for Trusts Work?
CRS reporting for trusts starts with one question: is the trust a Financial Institution or a Non-Financial Entity? If it’s a Financial Institution, the trust (or its trustee) reports its own account holders. If it’s a Passive NFE, every bank holding the trust’s money reports the trust’s controlling persons. Both routes name the same people.
The CRS treats a trust as an entity, even though most legal systems call it a relationship. Once it’s an entity, it has to fit one of the standard’s boxes. There are really only two that matter for private trusts.
| Classification | Typical trust | Who files the report | Who’s named |
|---|---|---|---|
| Financial Institution (managed Investment Entity) | Professional trust company as trustee, portfolio of shares, bonds or funds | The trust, usually through its trustee | Settlors, beneficiaries, protectors and anyone else with ultimate effective control (the “equity interest” holders) |
| Passive NFE | Family members as trustees, or a trust holding property, a company or plain cash deposits | Each bank or custodian where the trust holds an account | Settlors, trustees, protectors, beneficiaries and anyone else with ultimate effective control (the “controlling persons”) |
Each name goes to the tax authority of the country where that person is tax resident. A trust with a Canadian settlor, a Swiss protector and beneficiaries in Spain and Australia can generate reports to four different governments from one account. That’s why your tax residency country matters far more to CRS exposure than where the trust deed was signed.
One of the first things we explain to new clients is this split. A good share of the people who ask us about a trust want it for privacy from their own tax office. We tell them on the first call that CRS won’t allow that, and then we talk about what a trust is actually good for.
Is a Trust a Financial Institution Under CRS?
A trust is a Financial Institution under CRS when two tests are both met: its gross income comes mainly from investing or trading in financial assets, and it’s managed by another Financial Institution, usually a professional trust company or a discretionary fund manager. A trust with individual trustees holding a bank deposit isn’t one.
HM Revenue and Customs spells this out in its International Exchange of Information Manual (IEIM400800, updated 15 October 2026). The trust has to pass both the income test and the “managed by” test. From 1 January 2026, income from relevant crypto-assets counts toward the income test as well.
A few practical consequences follow from that wording:
- Professional trustee plus a portfolio: almost always a Financial Institution. The trustee usually handles the trust’s registration and reporting.
- Individual trustees plus a bank deposit: a Non-Financial Entity, because nobody with financial-institution status manages the assets.
- Professional trustee but only cash: HMRC says cash isn’t a financial asset, so a trust that only holds a depository account isn’t an Investment Entity even if a trust company runs it.
- Trust owning a holding company or real estate: usually a Passive NFE, since its income isn’t mainly from financial assets.
Classification changes who does the paperwork. It doesn’t change much about who gets named. People sometimes spend real money chasing a classification they think is “better” for privacy, which is wasted effort once you see the second half of the rules.
Who Gets Reported: Trust Controlling Persons Under CRS
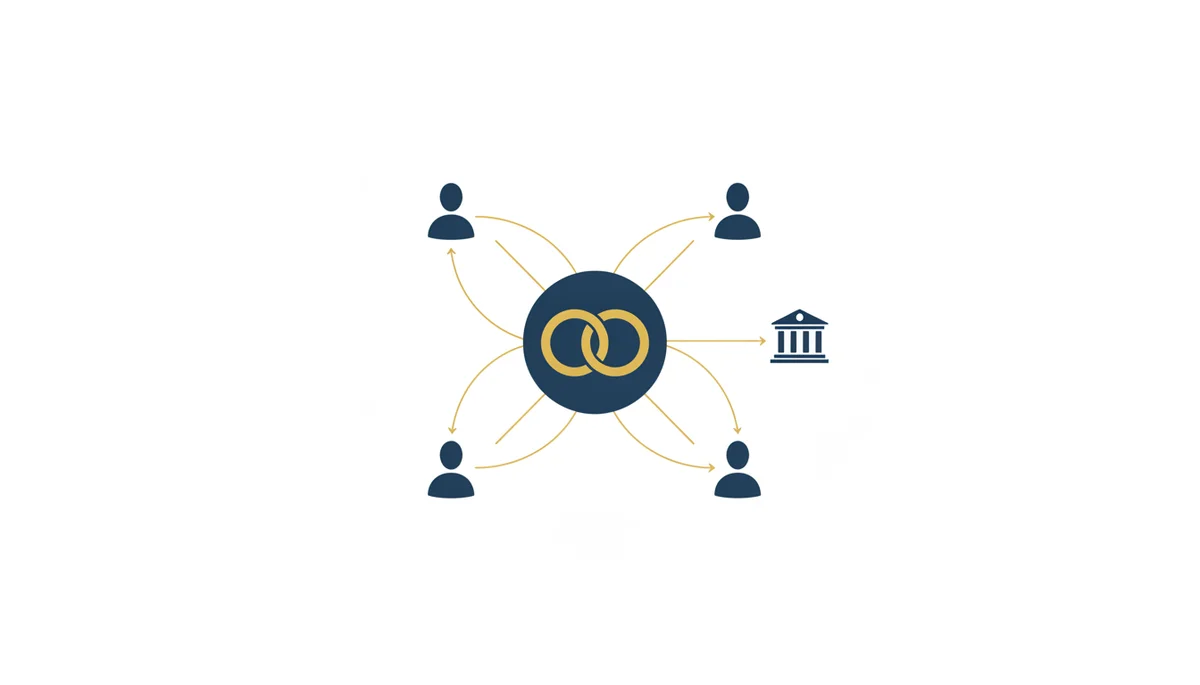
Trust controlling persons under CRS are the settlor, every trustee, any protector, the beneficiaries or class of beneficiaries, and any other natural person exercising ultimate effective control. A bank looks through a Passive NFE trust to all of them. For a trust that’s a Financial Institution, settlors, beneficiaries and protectors are reported as equity interest holders.
The definition comes straight from the standard and appears word for word in tax authority guidance, such as the Australian Taxation Office’s CRS glossary. The table below shows how each role is treated and what figure appears next to each name when the trust doesn’t calculate its own values, using the table in Singapore’s IRAS CRS FAQs (FAQ F.9).
| Role | Reported? | When | Balance shown (default basis) |
|---|---|---|---|
| Settlor | Yes | Every year the trust exists, even if irrevocable | Total value of all trust property |
| Trustee | Yes, as a controlling person | Every year | Total value of all trust property |
| Protector | Yes | Every year, whether or not they exercise control | Total value of all trust property |
| Mandatory beneficiary | Yes | Every year | Total value of all trust property |
| Discretionary beneficiary | Yes | In years they receive a distribution | Nil balance, plus the gross payment |
| Any other person with ultimate effective control | Yes | Every year | Total value of all trust property |
Those default figures come from the Financial Institution side of the rules. When a bank reports a Passive NFE trust, it shows the balance of the account it holds against each controlling person’s name.
Read that settlor row again. Each settlor’s line on the report can carry the value of the whole trust fund. A settlor who gave everything away years ago, and who can’t touch a cent of it, still appears in the data sent to their tax office.
Three more rules close the obvious gaps:
- Protectors are always in. The OECD’s CRS-related FAQs (Section VIII, D.6) say a protector of a trust that’s a Financial Institution is treated as an account holder “irrespective of whether it has effective control over the trust.”
- Company settlors get looked through. Where the settlor is a company, the people who control that company are identified and reported, and the OECD FAQs (Section I, Q7) say this applies in the year of settlement and every year after.
- Every role gets listed. HMRC’s guidance on reporting the roles of controlling persons (IEIM402184) says that where one person holds two roles in a trust, such as settlor and beneficiary, both roles are reported.
That last point matters more from 2026 onward, because the role itself is now part of the data (more on that below). The bank’s file won’t just say “controlling person.” It’ll say settlor, or protector, or beneficiary.
In practice, opening a bank account for a trust means a self-certification for the trust itself plus one for every controlling person, along with the deed and any letter of wishes the bank asks to see. Missing beneficiary details is the most common reason we see a trust account opening stall for weeks.
Discretionary Beneficiary CRS Reporting
Under discretionary beneficiary CRS reporting, a discretionary beneficiary is generally reported only for a year in which they receive a distribution, with the payment amount shown. A year with no distribution isn’t an account closure, so the beneficiary stays on file and reappears whenever money flows, as long as they aren’t permanently excluded.
That’s the OECD position in its CRS-related FAQs (Section I, Q6). For trusts that are Financial Institutions, the IRAS FAQs show the discretionary beneficiary with a nil balance and the gross payment reported in the year of distribution.
For Passive NFE trusts, there’s a wrinkle. The standard lets each country choose. Singapore, for example, lets banks report discretionary beneficiaries only in distribution years, but only if the bank has procedures to find out when distributions happen (IRAS FAQ F.8). If the trust doesn’t tell the bank in time, IRAS FAQ F.7 says the bank should report all discretionary beneficiaries in its records as controlling persons.
So the trustee’s housekeeping decides how much ends up in the file. A trustee who never sends distribution information to the bank can turn a quiet discretionary class into a full list of names reported every year.
Which Country Reports the Trust?
A trust that’s a Financial Institution is generally treated as resident wherever one or more of its trustees is tax resident, so the trustee’s country collects and sends the report. A Passive NFE trust’s data is reported by each bank or custodian in the country where the account sits.
The IRAS FAQs (B.1) put it plainly: a trust is considered resident in a participating jurisdiction “if one or more of its trustees are tax resident” there. That’s the reason trustee choice has CRS consequences. A trust whose only trustee is a Liechtenstein trust company reports through Liechtenstein’s tax administration, the same channel a Liechtenstein foundation uses.
Many trusts never register in their own right. Where the trustee is itself a reporting Financial Institution that takes on the trust’s due diligence and reporting, the trust can be a “trustee-documented trust” (IRAS FAQ G.6). The trust stays out of the registry, and the trustee files everything on its behalf. Nothing about the data changes.
What If the Trust Is Run From a Non-CRS Country?
A professionally managed trust that’s resident in a non-participating jurisdiction is always treated as a Passive NFE by the banks that hold its accounts. Those banks look through it and report its controlling persons, so running a trust from a country outside CRS doesn’t stop the people behind it from being reported.
HMRC’s guidance on new entity accounts and Passive NFE controlling persons (IEIM403480) says the rule exists to prevent controlling persons from avoiding reporting through entities set up in non-participating jurisdictions. The ATO glossary states the same rule for “Type B” Investment Entities.
The United States is the big example. It runs FATCA and hasn’t adopted the CRS. New Zealand’s Inland Revenue list of CRS reportable jurisdictions (updated 19 October 2026) runs to 113 jurisdictions with no United States on it. A trust with a South Dakota trust company as trustee isn’t reported by the US under CRS. But move that trust’s portfolio to a bank in Zurich or Singapore and the bank treats it as a Passive NFE, then reports the settlor, trustees, protector and beneficiaries to their home countries.
This is the reason a US bank account for non-residents gets attention in CRS discussions. The non-reporting comes from where the account is held, and it ends the moment money sits with a bank in a CRS country.
Advisers who design structures to get around this face another layer. The OECD’s Model Mandatory Disclosure Rules for CRS Avoidance Arrangements and Opaque Offshore Structures (9 March 2018) target exactly these arrangements, and countries that adopt them require disclosure. Anyone selling a trust as a way around CRS is selling something regulators wrote rules for years ago.
What Changed for Trusts Under the Amended CRS in 2026?
The OECD published an amended CRS in June 2023, and the UK and many other countries applied it from 1 January 2026, with first reports in 2027. For trusts, the main change is that banks must now report the role of each controlling person, so files show who’s the settlor, trustee, protector or beneficiary.
The OECD’s International Standards for Automatic Exchange of Information in Tax Matters (8 June 2023) package combined the new Crypto-Asset Reporting Framework with the CRS amendments. Those amendments brought certain e-money products and central bank digital currencies into scope, covered indirect crypto holdings through derivatives and investment vehicles, and strengthened due diligence and reporting.
HMRC’s CRS background page (IEIM400080) confirms the UK put the changes into law through The International Tax Compliance (Amendment) Regulations 2025, effective 1 January 2026. Under IEIM402184, role reporting starts for 2026, with a transitional rule for 2026 and 2027 limited to information held in a bank’s electronically searchable data, and it becomes mandatory for all controlling persons from 2028.
For trust settlors, the role field ends any ambiguity. Before, a tax office saw a name linked to a trust account. Now it sees “settlor” or “protector” next to that name, which tells an auditor where to start. We cover the wider package, including how it reaches crypto, in our guide to CRS 2.0.
Common Mistakes With CRS Reporting for Trusts
Most problems we see come from people who read half of the rules. These are the ones that cause the most trouble:
- Assuming an irrevocable trust removes the settlor. The settlor stays a controlling person, and on the default basis carries the full trust value, every year the trust exists.
- Naming yourself protector to keep a hand on the wheel. You’ve just added a second reported role. The OECD FAQ treats protectors as reportable regardless of control.
- Putting a company in as settlor. The bank looks through it to the people behind it, year after year.
- Treating “discretionary” as “invisible.” The first distribution puts the beneficiary on the report.
- Using a trustee in a non-CRS country and banking in a CRS one. The bank treats the trust as a Passive NFE and reports everyone anyway.
- Forgetting your own tax residency. Reports go to wherever each person is resident. Moving your tax residence changes which government receives your line, and dual residents can end up reported to both.
CRS Reporting for Trusts: Scenario Comparison
The table below applies the rules above to the six trust setups we’re asked about most often. It’s a summary of the standard, and each trust’s facts can shift the result, so treat it as a starting point for a conversation with whoever does your trust’s reporting.
| Setup | Likely classification | Reported by | Who’s named |
|---|---|---|---|
| Cook Islands trust, licensed trust company as trustee, investment portfolio | Financial Institution | Trust company in the Cook Islands | Settlor, protector, mandatory beneficiaries, discretionary beneficiaries in distribution years |
| Family trust, two relatives as trustees, savings account in the UK | Passive NFE | UK bank | Settlor, both trustees, protector, beneficiaries |
| Trust company as trustee, trust holds only a cash deposit | Not an Investment Entity (cash isn’t a financial asset) | The bank, if the trust is a Passive NFE | Controlling persons |
| Trust owns a BVI company that owns real estate | Usually a Passive NFE | Banks holding the trust’s and company’s accounts | Trust’s controlling persons, looked through at each level |
| US trust company as trustee, portfolio held with a US broker | Not reported under CRS (US is outside CRS) | Nobody under CRS (FATCA rules apply separately) | Nobody under CRS |
| US trust company as trustee, portfolio at a Swiss bank | Passive NFE (non-participating Investment Entity rule) | Swiss bank | Settlor, trustees, protector, beneficiaries |
If you’re weighing jurisdictions, our pages on the Cook Islands trust and the Cyprus International Trust cover how each one handles creditor protection, which is where a trust earns its keep.
How to Prepare a Trust for CRS Reporting
Preparing a trust for CRS reporting comes down to five things: work out its classification, collect a self-certification from every controlling person, confirm each person’s tax residency, set up a way to tell the bank about distributions, and keep the deed and records ready for the bank’s review. Each step takes days and avoids months of frozen accounts.
Step 1: Classify the trust. Ask whether a Financial Institution manages it and whether its income mainly comes from financial assets. Get the trustee’s answer in writing.
Step 2: Collect self-certifications. The trust needs one, and so does every settlor, trustee, protector and named beneficiary, each with a tax identification number.
Step 3: Confirm tax residency. Each person’s line goes to their own tax office, so a stale address or an old residency claim creates a report to the wrong country and a mismatch someone will query.
Step 4: Set up distribution notices. Agree with the bank how and when the trustee reports discretionary distributions, so the bank doesn’t fall back on reporting the whole beneficiary class.
Step 5: Keep the file current. Tell the bank about new beneficiaries, a new protector or a change of trustee when it happens, since each one changes who’s reported.
Our trusts and foundations service builds this file at setup, because fixing it after a bank has frozen an account takes far longer.
CRS Reporting for Trusts: Frequently Asked Questions
Does CRS reporting for trusts include the settlor?
Are trustees reported under CRS?
Is a trust a financial institution under CRS if it has a professional trustee?
How does discretionary beneficiary CRS reporting work?
Is the protector of a trust reported under CRS?
Can a trust avoid CRS by using a US trustee?
What changed in CRS reporting for trusts in 2026?
Which country receives the CRS report about my trust?
Final Thoughts
The CRS was built with trusts in mind, and the drafters closed the routes people tried first: excluded settlors, company settlors, quiet protectors, trustees in non-CRS countries. Every one of them is covered in the standard or its official FAQs.
That doesn’t make trusts pointless. A well-built trust still separates legal ownership from benefit, keeps assets out of a probate fight, and puts real distance between your wealth and a future creditor. Those are the jobs it was designed for. If what you want is less reporting, the lever is where you and your family are tax resident and where the money is banked, and that’s a different plan from the trust deed. Our asset protection guides cover both sides.
Sources and References
- HM Revenue and Customs, IEIM400800: Investment Entity: Trusts (updated 15 October 2026)
- HM Revenue and Customs, IEIM402184: Reportable Information: Role(s) of Controlling Persons
- HM Revenue and Customs, IEIM403480: Due Diligence: New Entity Accounts: Passive NFE, Controlling Persons (updated 15 October 2026)
- HM Revenue and Customs, IEIM400080: Background: Common Reporting Standard
- OECD, CRS-related Frequently Asked Questions (as published by the Turks and Caicos Islands competent authority)
- Inland Revenue Authority of Singapore, IRAS FAQs on the Common Reporting Standard (23 October 2021)
- Australian Taxation Office, Automatic exchange of information (CRS and FATCA): Glossary
- OECD, International Standards for Automatic Exchange of Information in Tax Matters: Crypto-Asset Reporting Framework and 2023 update to the Common Reporting Standard (8 June 2023)
- OECD, Model Mandatory Disclosure Rules for CRS Avoidance Arrangements and Opaque Offshore Structures (9 March 2018)
- Inland Revenue (New Zealand), CRS reportable jurisdictions (updated 19 October 2026)